⏱ 4-minute read · open “Read more” for the details
This post is for the people behind the scenes: the banks, card processors and product teams who run the systems that move money back when flights are cancelled. When thousands of flights are cancelled in one day, the payment system doesn’t just get busier. Two different waves hit it at the same time, from opposite directions.
After mass cancellations, airlines push refunds out while customers ask their banks to pull money back. Both go through the same card networks, with different messages, rules and deadlines. This post walks through each one, from the bank’s side.
Two waves at once
Meet Anna. Her flight from Chicago is cancelled, along with thousands of others. She paid $420 by card. Two things now race each other to get her money back.
- Wave 1: the airline sends refunds back to customers’ cards.
- Wave 2: customers who don’t see their money ask their bank for a chargeback.
- If both land, the customer is paid twice, and one must be undone later.
Read more: Two waves at once
- Wave 1, refunds: the airline (the merchant) sends credits back to customers’ cards. The airline starts these.
- Wave 2, disputes: customers who don’t see their money call their bank, and the bank (the issuer) starts a chargeback. The customer’s bank starts these.
The two waves race each other. If the airline’s refund and the bank’s chargeback both land, the customer is paid twice, and one of them has to be undone later. Most of the operational pain after a mass cancellation comes from that race.
The big picture
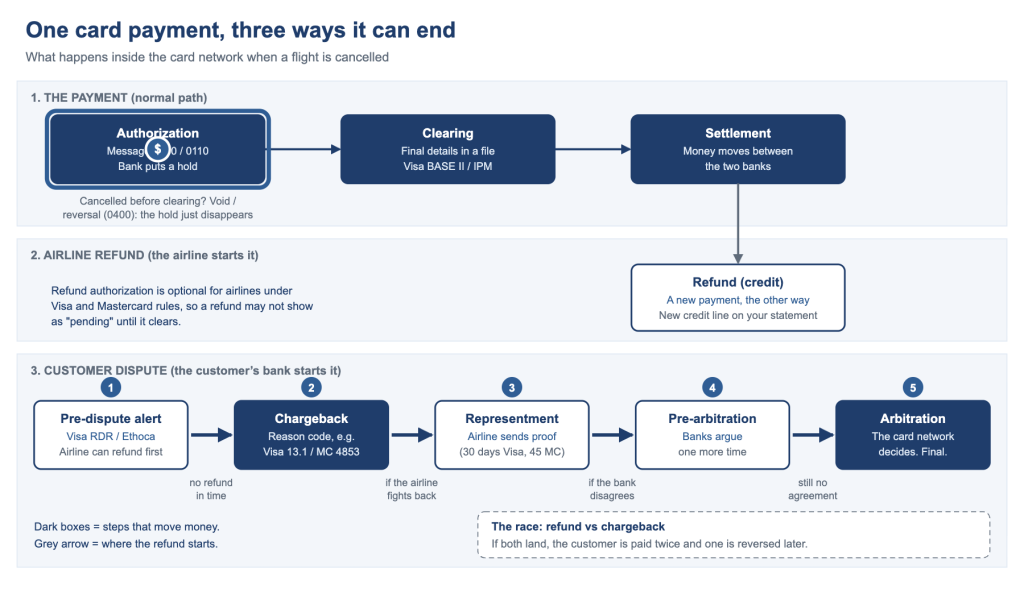
Here is the whole picture on one page: who sends money back, and who pulls it back.
- The airline and its bank (the acquirer) send refunds.
- Anna’s bank (the issuer) starts disputes.
- Visa and Mastercard carry both, each with its own rules and deadlines.
Message by message: how a card payment really works
Anna’s $420 payment happened in two steps: an approval, then a separate file that moved the money. That split decides how it can be undone.
- If the money hasn’t moved yet, the hold is simply released.
- If it has moved, the airline must send a refund.
- Airlines don’t have to send a refund approval message, so Anna may not see the refund for days.
Read more: Message by message: how a card payment really works
A card payment is a “dual message” process: one message to approve, and a separate file later to actually move the money. That split is why a cancelled flight can be undone in different ways depending on timing.
| Stage | What happens | How it is undone |
|---|---|---|
| Authorization | A real-time message (ISO 8583 0100, answered by 0110). The customer’s bank approves and puts a hold on the money. | An authorization reversal (message 0400) releases the hold. The “pending” line just disappears. |
| Clearing | A batch file from the airline’s bank to the network (Visa BASE II, or Mastercard IPM files) with the final amount. Fees between banks are worked out here. | Too late for a reversal. Only a refund or a chargeback can bring the money back. |
| Settlement | Money actually moves between the two banks, usually a day or two after purchase. | Same as clearing. |
| Refund | A new credit payment going the other way, linked to the original. | It is the undo, started by the airline. |
Here is a detail that confuses customers. Visa and Mastercard make most merchants send an approval message for a refund, so the customer sees it straight away. For airlines, it is optional. So an airline refund may never show as “pending”. It just appears days later, when it clears. That gap is exactly when worried customers call their bank and open a dispute.
The dispute workflow, from inside the network
A week later, Anna still sees nothing. She calls her bank, and it opens a dispute.
- Visa sorts disputes into four groups: fraud, authorization, processing errors and consumer disputes.
- Banks work the cases in Visa Resolve Online or Mastercom.
- Network rules set strict deadlines for each side.
Read more: The dispute workflow, from inside the network
Visa sorts every dispute into four groups: fraud, authorization, processing errors and consumer disputes. Fraud and authorization disputes follow an automatic path called Allocation, where Visa decides who pays from its own data. The other two follow Collaboration, where the merchant can send evidence and the card issuer decides. A cancelled flight is a consumer dispute, so the airline’s evidence really matters.
| What happened | Visa reason code | Mastercard |
|---|---|---|
| Flight cancelled, no refund | 13.1 Merchandise/Services Not Received, or 13.7 Cancelled Merchandise/Services | 4853 Cardholder Dispute (goods or services not provided) |
| Airline promised a refund, but it never arrived | 13.6 Credit Not Processed | 4853 Cardholder Dispute (credit not processed) |
The banks work these cases in each network’s own dispute system (Visa Resolve Online for Visa, Mastercom for Mastercard). The deadlines are set by network rules:
| Step | Visa | Mastercard |
|---|---|---|
| Issuer files the chargeback | Usually within 120 days of the charge, or of the date the service should have happened (never more than 540 days after the charge) | Usually within 120 days |
| Airline’s side responds (representment) | 30 days | 45 days |
| If still disputed | Pre-arbitration, then arbitration, where Visa decides | Pre-arbitration, then arbitration, where Mastercard decides |
Stopping chargebacks before they happen
Smart airlines refund Anna before her dispute turns into a chargeback.
- Visa’s Rapid Dispute Resolution refunds eligible disputes automatically, using rules set in advance.
- Mastercard’s Ethoca Alerts warn the airline early when a customer disputes.
- Fewer chargebacks mean lower fees and fewer double refunds.
Read more: Stopping chargebacks before they happen
Both networks own tools that let a merchant refund a disputed charge before it becomes a formal chargeback:
- Rapid Dispute Resolution (RDR) from Verifi, a Visa company, refunds eligible Visa disputes automatically, based on rules the merchant sets in advance.
- Ethoca Alerts, from a Mastercard company, warn the merchant when a customer disputes, so it can refund first and close the alert.
- American Express runs its own program for its cards.
During a mass cancellation, one simple rule can stop thousands of chargebacks: “auto-refund any dispute on a cancelled flight that hasn’t been refunded yet.” The customer gets paid sooner, and the airline avoids chargeback fees and a worse dispute ratio.
The law layer on top
Anna also has the law on her side.
- For credit cards, she has 60 days from her statement to dispute in writing.
- Her bank must acknowledge within 30 days and resolve within two billing cycles (90 days at most).
- The law’s clock runs inside the network’s 120 days, so banks follow the law first.
Read more: The law layer on top
- Credit cards: the Fair Credit Billing Act (Regulation Z) gives the customer 60 days from the statement to dispute in writing. The bank must acknowledge within 30 days and resolve within two billing cycles, at most 90 days.
- Debit cards: Regulation E mainly covers unauthorized transfers and errors. For a “service not provided” case like a cancelled flight, the customer usually relies on the card network’s dispute rules and the bank’s own policy, not the law.
- Airline refunds: under US Department of Transportation rules, the airline must refund automatically: within 7 business days for credit cards, 20 days for other payment types.
Notice the clocks: the law’s 60 days starts before the network’s 120 days run out. So a bank’s dispute intake must follow the law’s timeline first.
What breaks at scale
Now multiply Anna by thousands. Operations queues fill up with the same problems.
- Double credits: the refund and the chargeback both land.
- Refunds that can’t be matched to the original payment.
- Deadlines missed because teams are swamped.
Read more: What breaks at scale
These are the cases that pile up in operations queues after a mass cancellation:
- Double credits: refund and chargeback both land. Match them on the Acquirer Reference Number (ARN, the unique ID the acquirer gives each card transaction) and the amount before paying out, and reverse one if both go through.
- Provisional credits: the bank credits the customer while the case runs. If the airline then proves it already refunded, the bank must take that credit back, and explain it in writing.
- Currency differences: a ticket bought in another currency can come back as a slightly different amount, because the exchange rate changed between purchase and refund.
- Partial refunds: fare refunded, but seat fees, bag fees or taxes not yet. One booking can mean several credits.
- Split payments: part card, part voucher, part miles. Only the card part goes back to the card.
- Closed or replaced cards: the refund still goes to the account behind the card, not to a new card number by magic. Banks need a rule to route it.
- Travel websites: if a travel website sold the ticket, it is the merchant on the statement, not the airline, so the dispute goes to the website’s bank.
- Merchant risk: airlines are paid when you book, but fly later. If an airline fails, the airline’s bank can be left with the chargebacks, which is why acquirers watch airline risk closely.
The FDE playbook: fix it fast for the customer and the travel company
If an airline or a bank called me the morning after, I wouldn’t write a report. I’d sit with the team and ship fixes in days.
- First, join the booking, payment and dispute data in one view.
- Then take quick wins, such as auto-refund rules for the cancelled flights.
- Protect the travel company’s cash too.
- Measure refund time, double credits and the chargeback rate.
Read more: The FDE playbook: fix it fast for the customer and the travel company
A Forward Deployed Engineer (FDE) doesn’t write a report about the problem. They sit with the operations team, get the data, and ship a fix in days. If an airline, a travel website or a bank called me the morning after a mass cancellation, this is how I would work.
First, see the whole problem in one place
Most of the pain comes from three systems that don’t talk to each other. The booking system knows who was on the cancelled flights. The payment system knows what was refunded. The card networks’ dispute feed knows who complained to their bank. So the first job is to join them, using the booking reference and each card payment’s ARN, into one simple view:
| Booking | What we see | Next action |
|---|---|---|
| A | Cancelled, no refund yet, no dispute | Refund now and tell the customer |
| B | Refund sent, and a dispute is open | Send the refund proof and close the dispute |
| C | No refund yet, and a dispute is open | Refund through the alert, before it becomes a chargeback |
| D | Customer rebooked and flew, but still disputes | Send proof the customer flew |
Once every booking has a “next action”, the team stops guessing and starts clearing the list.
Then, the quick wins
| Action | How it helps the customer | How it helps the airline or travel company |
|---|---|---|
| Refund first, in batches, for everyone cancelled and not rebooked, without waiting for them to ask | Money back within days, no calls | Fewer disputes, fewer chargeback fees, and it meets the US 7-day rule for card refunds |
| Send a refund authorization message, even though it’s optional for airlines | The refund shows as “pending” at once, so they stop worrying | Customers who can see their refund don’t open disputes |
| Turn on auto-refund rules for pre-dispute alerts (Visa RDR, Ethoca) on cancelled bookings | Their bank complaint is solved in hours, not weeks | No chargeback, no fee, no hit to the dispute ratio |
| Tell people clearly and early: one message by email, text and app with the refund amount, the date, and the exact name it will show on the statement | They know what to expect and what to look for | Far fewer calls to the contact center, and fewer “I don’t recognize this” disputes |
| Warn about scams in the same message: “we will never ask for your card number or a code” | Protects them from fake helplines | Protects the brand from being used by scammers |
| Run the double-credit check every day, matching refunds and disputes | No surprise money taken back weeks later | No paying the same refund twice |
| Answer every dispute with proof (refund reference, or proof the customer flew) before the deadline | Their case is closed quickly either way | Wins the disputes it should win, instead of losing by default |
For the customer’s bank
- Tag the cases. Give every dispute about the cancelled flights a “mass cancellation” tag, so they can be handled together with one script.
- Check before filing. Look at the account first: if the airline’s refund has already posted, tell the customer instead of opening a chargeback.
- Give the provisional credit quickly where the case is clear, so the customer isn’t out of pocket while the case runs.
- Talk to the airline’s side through the network’s alert tools, instead of sending thousands of formal chargebacks.
Don’t forget the travel company’s money
A mass cancellation means refunding days of ticket sales at once. That hits the airline’s or travel website’s cash, and its bank (the acquirer) may hold back more money as a safety reserve. So a good FDE plan also gives finance a daily number: refunds sent, refunds still to send, and disputes open. Then nobody is surprised.
How I would measure it
- Time to refund: days from cancellation to money back. Target: within the legal deadline, ideally much sooner.
- Dispute rate: disputes as a share of cancelled bookings. It should fall every day.
- Double credits: how many were caught before payout. The goal is zero paid twice.
- Calls to the contact center about refunds. Clear messages bring this down fast.
The goal isn’t to “win” against the customer. When the customer gets their money quickly and clearly, the airline wins too: fewer chargebacks, lower fees, less work, and a customer who will fly with them again.
Under the hood: what an FDE would actually build
For engineers, here is how those fixes are built, on top of the systems the airline already has.
- One data view that joins the three systems.
- Event-driven updates, so nothing waits for a nightly batch.
- Refunds that are safe to retry, plus dashboards and alerts from day one.
Read more: Under the hood: what an FDE would actually build
The playbook above is the “what”. This is the “how”: the small pieces of engineering I would ship in the first week. None of it needs a big new platform. It sits on top of the systems the airline and its bank already have.
For engineers: the technical detail below is optional; the rest of the post makes sense without it.
1. One data view that joins three systems
Booking data, refund records and the dispute feed from the networks (Visa Resolve Online, Mastercom) are joined on the booking reference and the ARN (Acquirer Reference Number, the unique ID of each card payment). Every cancelled booking gets one “next action”.
-- One row per cancelled booking, with the next action
SELECT b.booking_ref,
       b.ticket_no,
       p.arn,                       -- Acquirer Reference Number of the original sale
       p.amount, p.currency,
       r.refund_id, r.status   AS refund_status,
       d.case_id,  d.reason_code, d.respond_by,
       CASE
         WHEN b.flown = 1                       THEN 'SEND_PROOF_FLOWN'
         WHEN r.refund_id IS NULL AND d.case_id IS NULL THEN 'REFUND_NOW'
         WHEN r.refund_id IS NULL AND d.case_id IS NOT NULL THEN 'REFUND_VIA_ALERT'
         WHEN r.refund_id IS NOT NULL AND d.case_id IS NOT NULL THEN 'SEND_REFUND_PROOF'
         ELSE 'MONITOR'
       END AS next_action
FROM   bookings b
JOIN   payments p   ON p.booking_ref = b.booking_ref
LEFT JOIN refunds r ON r.original_arn = p.arn
LEFT JOIN disputes d ON d.arn = p.arn
WHERE  b.flight_status = 'CANCELLED'
  AND  b.rebooked = 0;
2. Event-driven, so nothing waits for a nightly batch
Each step publishes an event, and each team reads only what it needs, for example on Kafka topics:
flight.cancelled: from the operations system, the trigger for everything elserefund.requestedandrefund.cleared: from the payment systemdispute.receivedanddispute.closed: from the network dispute feedcustomer.notified: from the messaging service
The “next action” view updates the moment any of these events arrives, not the next morning.
3. Refunds that are safe to retry
During a surge, timeouts and retries are normal. Every refund call carries an idempotency key built from the booking and ticket, so the same refund can be retried safely and is never paid twice.
// Refund API: safe to retry, never pays twice
POST /refunds
Idempotency-Key: REF-{booking_ref}-{ticket_no}-FULL

{
  "original_arn": "74xxxxxxxxxxxxxxxxxxxxx",
  "amount": 412.60,
  "currency": "USD",
  "reason": "FLIGHT_CANCELLED"
}

// Same key again (timeout, retry, double click)
// -> returns the first result, no second refund
Refund batches are also throttled to the rate the acquirer can accept, with retries that wait a little longer each time (exponential backoff). Flooding the acquirer just creates more timeouts.
4. Timeouts that clean up after themselves
On a slow network, the fix for “charged twice” is in the message flow, not in the call center:
// Card terminal or gateway: no answer in time
send  0100  (authorization request, with STAN + RRN)
wait  up to N seconds for 0110
if no 0110:
    send 0400 (reversal) with the SAME STAN + RRN
    show "Payment not completed. You have not been charged."
// Refund authorization (optional for airlines, but helps):
send  0100 with processing code 20 (credit / refund)
5. Auto-refund rules, scoped to the event
Pre-dispute rules are powerful, so keep them narrow: only this airline’s category code, only consumer disputes, only bookings that were cancelled, not flown and not yet refunded, and never more than the original amount.
# Pre-dispute auto-refund rule (Visa RDR / Ethoca), for this event only
IF  merchant_category      = 4511          # airlines
AND dispute_category       = consumer       # not fraud
AND booking.flight_status  = CANCELLED
AND booking.flown          = false
AND refund_already_sent    = false
AND amount                 <= original_amount
THEN accept_and_refund      # closes the case before it becomes a chargeback
6. Dashboards and alerts from day one
| Metric | Alert when |
|---|---|
| Refunds still to send | Not falling day by day |
| Oldest unrefunded cancelled booking | Close to the 7-day legal deadline for card refunds |
| Disputes with a response due in 3 days or less | Any without evidence attached |
| Double credits (refund and chargeback on the same ARN) | More than zero paid out |
| Refund API errors and timeouts | Above normal for 15 minutes |
7. Example data mappings
Most of the real work is mapping fields between systems that were never designed to talk to each other. Here are the two mappings that matter most. The field names are typical examples; every airline and bank names them a little differently.
Cancellation data to refund request. One cancelled flight becomes one refund per unflown ticket:
// Event from the airline's operations system
{
  "event": "flight.cancelled",
  "flight_no": "XX1234",
  "dep_date": "2026-11-26",
  "origin": "EWR", "destination": "ORD",
  "cancel_reason": "CREW",            // airline-controlled
  "cancelled_at": "2026-11-26T05:40:00-05:00",
  "bookings": [
    { "booking_ref": "ABC123", "ticket_no": "0161234567890",
      "pax": 2, "rebooked": false, "flown": false }
  ]
}
// Refund request built from it
{
"idempotency_key": "REF-ABC123-0161234567890-FULL",
"original_arn": "74xxxxxxxxxxxxxxxxxxxxx",
"amount": 412.60, // fare + taxes + paid extras not used
"currency": "USD", // same currency as the original charge
"refund_to": "ORIGINAL_CARD", // never a different card
"reason": "FLIGHT_CANCELLED",
"due_by": "2026-12-07" // 7 business days for card refunds
}| Cancellation field | Refund field | Rule |
|---|---|---|
| booking_ref + ticket_no | idempotency_key | One refund per ticket, safe to retry |
| booking_ref (looked up in payments) | original_arn | Links the refund to the original card payment |
| rebooked, flown | (no refund) | Skip if the customer rebooked or flew |
| cancel_reason | reason, plus extras | If the airline caused it, also refund unused paid extras |
| cancelled_at | due_by | Card refunds: 7 business days |
Dispute data to internal action. Each dispute from the network is matched to the booking and the refund on the ARN, then mapped to one action:
// Typical fields in a dispute record from the network feed
{
  "case_id": "D-000123",
  "network": "VISA",
  "arn": "74xxxxxxxxxxxxxxxxxxxxx",
  "reason_code": "13.1",
  "amount": 412.60, "currency": "USD",
  "stage": "FIRST_CHARGEBACK",
  "respond_by": "2026-12-28"
}
# Map a network dispute to an internal action
REASON_MAP = {
("VISA", "13.1"): "SERVICE_NOT_PROVIDED",
("VISA", "13.6"): "CREDIT_NOT_PROCESSED",
("VISA", "13.7"): "CANCELLED_SERVICE",
("MASTERCARD", "4853"): "CARDHOLDER_DISPUTE",
}
def next_action(dispute, booking, refund):
category = REASON_MAP.get((dispute["network"], dispute["reason_code"]), "OTHER")
if booking["flown"]:
return "REPRESENT_WITH_BOARDING_RECORD"
if refund and refund["status"] in ("AUTHORIZED", "CLEARED"):
return "REPRESENT_WITH_REFUND_PROOF" # refund ID, date, amount
if category in ("SERVICE_NOT_PROVIDED", "CANCELLED_SERVICE",
"CREDIT_NOT_PROCESSED", "CARDHOLDER_DISPUTE"):
return "ACCEPT_AND_STOP_REFUND" # bank already returned the money
return "MANUAL_REVIEW"| What we find | Action | Evidence to send |
|---|---|---|
| Customer flew | Represent | Boarding record |
| Refund already sent | Represent | Refund ID, date and amount |
| No refund yet | Accept the chargeback, and stop the planned refund | None: the bank has already returned the money |
| Anything else | Manual review | Depends on the case |
The rule “accept the chargeback and stop the planned refund” is the one teams forget. Without it, the refund batch pays the customer a second time.
The win isn’t any single piece. It’s that the airline’s team, the bank’s team and finance all look at the same numbers, in real time, and every problem has an owner and a next step.
When the airport network slows down
Meanwhile, Anna is at the airport paying for a hotel. Thousands of people share the same Wi-Fi, and payments slow down.
- A slow network can make a payment look failed when it went through.
- Tip: don’t tap again straight away. Check your banking app for a pending charge first.
- A second charge usually drops off on its own within a few days.
Read more: When the airport network slows down
After mass cancellations, airports fill up. Thousands of people are on the same mobile network and the same Wi-Fi, all trying to rebook, pay for food and hotels, and check their refunds. The network slows down, and payments start to fail in ways that look like bugs.
| What goes wrong | Why it happens | How to fix it |
|---|---|---|
| Charged twice for one coffee or hotel night | The card machine waits too long, shows “error”, and the customer taps again. But the first payment actually went through. | If no answer comes back in time, the system cancels the first payment automatically (a reversal). And every payment carries a unique ID, so a retry is never counted twice. |
| Card machines stop working | The terminal can’t reach the bank. | Let terminals approve small payments offline and send them later, within the limits the card networks allow. Have a backup connection, such as a second mobile network. |
| Security codes arrive late | Text messages with one-time codes are delayed on a busy network, so online payments time out. | Offer approval in the bank’s app instead of by text, and give the code a longer time to work. |
| The app or website won’t load | Heavy pages and big images on a slow network. | A light “cancellation mode” page: rebook, refund status and help, with almost nothing else on it. |
| Refund status checks fail | Everyone checks at once, and the app times out. | Send the status to customers by email or push notification, so they don’t need to keep checking. |
A tip for travelers: if the card machine shows an error, don’t tap again straight away. Check your banking app for a “pending” charge first. If you do see two, the second one usually drops off on its own within a few days, because it was never completed.
Spotting fraud in the chaos
When thousands of refunds go out at once, fake ones are easy to hide.
- Paid twice: a refund from the airline and from the bank.
- Fake airline staff on helplines, social media or texts.
- Stolen accounts used to redirect refunds.
Read more: Spotting fraud in the chaos
When thousands of refunds go out at once, fake ones are easy to hide. Watch for four kinds of fraud:
- Paid twice: a customer takes the airline’s refund and also gets money back from their bank.
- Fake airline staff: scammers on fake helplines, social media or texts who steal card details and codes.
- Stolen accounts: a criminal logs in to a customer’s airline account and sends the refund somewhere else.
- Insiders: a staff member sends “refunds” to their own card.
| Red flag | What to do |
|---|---|
| Refund going to a different card than the one that paid | Refund only to the original card. Exceptions need a second approver. |
| More refunded than was paid, or two refunds for one ticket | Block it. Refunds can never be more than the original payment. |
| A refund and a dispute on the same payment | Match them every day, and send the refund proof to the bank. |
| A dispute from someone who actually flew | Send the boarding record as proof. |
| Email or phone changed just before a refund request | Pause the refund and check with the customer first. |
| Many refunds landing on one card from different bookings | Stop and investigate. |
The most important control is simple: one person creates a manual refund, a different person approves it. I’ve seen what happens when that check isn’t really there; I tell the story in my post on the 10 payment controls. On a busy day, keep it switched on.
And remember: fast and safe can go together. Automatic refunds to the original card are both. Only the exceptions need the extra check.
What I would test
Before the next storm season, I would test these cases end to end.
- Cancel before clearing: the hold is released and no refund is sent.
- A full refund after settlement, linked to the original payment.
- A refund that lands while a chargeback is open: the double credit is caught.
Read more: What I would test
From a testing point of view, these are the scenarios I would put through any issuer, acquirer or airline payment system before the next storm season:
- Cancel before clearing: the authorization reversal releases the hold, and no refund is sent.
- Full refund after settlement, linked to the original transaction.
- Refund lands while a chargeback is open: the double credit is caught and one side is reversed.
- Chargeback filed after a refund already posted: the airline’s representment shows the refund and wins.
- Partial refunds (fare only, then fees) on one booking.
- Refund in a foreign currency with a different exchange rate.
- Refund to a closed or reissued card.
- A pre-dispute alert (RDR or Ethoca) auto-refunds, and no chargeback is created.
- A refund to a different card than the one that paid is blocked, or sent for a second approval.
- A manual refund above the limit can’t be approved by the person who created it.
- Slow network: the card machine gets no answer in time, and the first payment is reversed automatically, so the customer is never charged twice.
- Volume test: ten times the normal refund and dispute volume in one day, with queues, alerts and customer messages still working.
My take
From the outside, a cancelled flight looks like one customer and one refund. From inside the bank, it’s two systems racing each other: refunds going out and disputes coming in. The banks and airlines that do well are the ones that match the two, refund early, and tell customers clearly what’s happening, before the call center does it for them.
Working on a payments project?
I help banks and fintechs deliver real-time payments, ISO 20022, and AI-driven AML and compliance change, from strategy to go-live.
Connect on LinkedInSee how I can help